How to Determine Return on Investment of a Short-Term Rental Home
How to work out what renting your home short-term could return: revenue, fees, taxes and costs, with a hypothetical example and a payback check.
 Justin Feldstein
Founder, Haus Vacation Rentals · Licensed NYS Real Estate Broker
If you own a home in the Hudson Valley and are wondering whether to rent it short-term, the useful question is not a textbook percentage. It is: after everything that comes off, how much cash does the home produce, and how long does it take to cover what it costs to get started? This post walks through that math in the order we would do it with an owner.
Decide what you are comparing
For a home you already own, the purchase price is a sunk cost. What matters is the difference between what the home does for you now and what it could do as a rental. The alternatives are usually one of these: keeping it for your own use, renting it on a long-term lease, or leaving it mostly empty. Each has its own costs, so write them down before you compare.
Use only the costs that renting adds or changes. Your mortgage and property taxes exist either way. Extra cleaning, supplies, utilities during guest stays, management fees and furnishing are what the rental adds.
Start with revenue, honestly
Revenue depends on the home, the town, the season and how many nights you make available. Across the markets we work in, annual rental revenue for whole homes runs from roughly $65,000 to $200,000 or more. That is a market-level range, not a forecast for your home, and the gap between the low end and the high end is the whole question.
Build your own figure from nights available, expected occupancy and average booked rate, season by season. We explain how in What Could Your Hudson Valley Home Earn on Airbnb?. Haus asks that the home be available for rental at least 180 nights a year, and that is an availability requirement, not a booking guarantee.
List what comes off
Between revenue and your pocket there are several layers. Taking them in order keeps you from comparing a gross number to someone else's net one.
- Guest-paid taxes and platform fees. Taxes collected from guests are not your revenue. Platform fees reduce what the home collects.
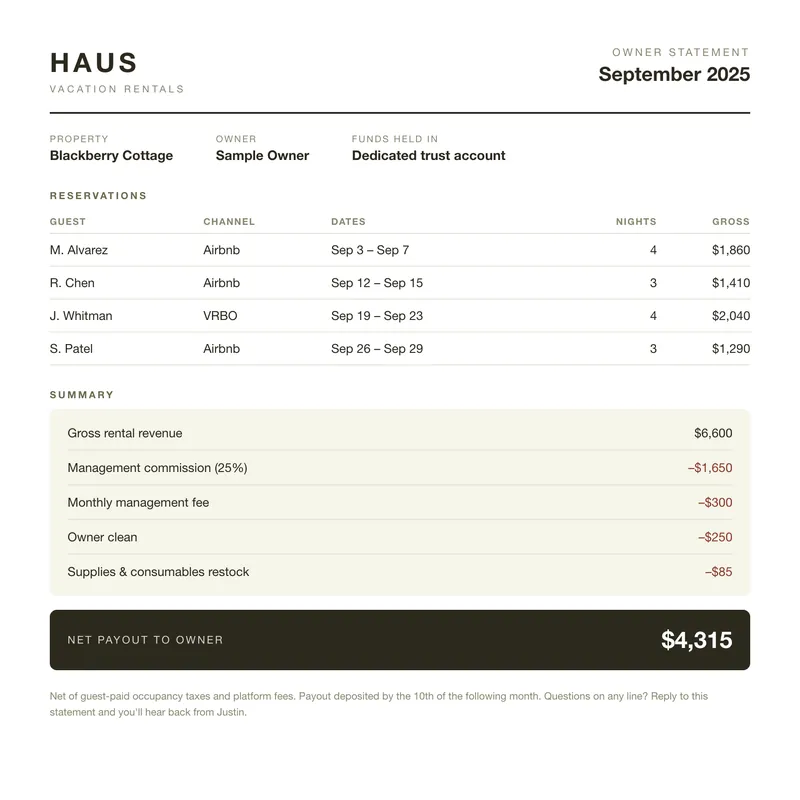
- Management. Haus charges 25% of the rent the home collects, after guest-paid taxes and platform fees, plus a monthly property management fee of $250 to $400 depending on home size, and a one-time $1,500 onboarding fee. The monthly fee rises 5% each anniversary. Guests pay the cleaning fee and Haus retains it. Situational charges, such as a 10% coordination fee on larger third-party invoices, are on the fees page.
- Operating costs. Utilities, supplies, insurance, snow and lawn care, repairs, and a reserve for surprises.
- Setup. Furnishing, photography, safety equipment and any work the home needs before the first guest. Our rent-ready guide lists the common items.
- Local compliance. Permit fees and inspections in your town, and the occupancy tax filings described in our Ulster County occupancy tax guide.
A hypothetical example
The numbers below are made up to show the method. They are not an estimate for any home.
- Rent collected in a year: $48,000.
- Management commission at 25%: $12,000.
- Monthly fee at $300 for 12 months: $3,600.
- Left after management: $32,400.
- Onboarding fee in year one: $1,500, leaving $30,900.
- Operating costs the rental adds (utilities, supplies, insurance, upkeep): $20,000, leaving $10,900.
Say getting the home ready costs $15,000 in furnishings and work. Dividing $15,000 by $10,900 gives about 1.4 years, or 16 to 17 months to earn back the setup cost, if every year looks like this one. That is a payback period, and for an owner it is usually more useful than a percentage return, because it shows how long your cash is at risk.
Now change one input. If rent collected is $36,000 instead, the commission is $9,000, the monthly fee is still $3,600, and after the onboarding fee and the same $20,000 of costs you are left with about $1,900 in year one. The business can look fine on a good-year number and thin on a modest one. Run the lower case before you commit.
The same worked example, using $60,000 of rent, is on our fees page.
Taxes
Rental income is generally reported on Schedule E, and the IRS describes the common deductions in Topic No. 414, Rental Income and Expenses. Special rules apply if you also use the home yourself, including a rule for homes rented fewer than 15 days a year, covered in IRS Publication 527. Local lodging taxes are separate from income tax. This is general information, not tax advice. Confirm how it applies to you with your CPA before you rely on any of these figures.
If you are buying a home to rent
The same method applies, with two changes. Include the purchase price, closing costs and financing as part of your cash in, and check the town's short-term rental rules before you make an offer, because some towns cap or prohibit rentals. Our Ulster County rules by town and the regulations overview are a starting point. We do not offer investment advice.
Want a second set of eyes on your numbers?
Tell us about your home and what you hope to do with it. Justin reviews every home personally and replies within 3 business days. Tell us about your home.